Key Insights
- Infrastructure matters more than issuance
Community banks can access stablecoin payment capabilities without developing independent blockchain systems.
- Payment demand is driving adoption
Moov said businesses already seek stablecoin acceptance and disbursement through their financial institutions.
- Compliance remains unresolved
Banks need to identify who is responsible for customer identification, sanctions screening, transaction monitoring and reporting of suspicious transactions.
Coinbase will work with payments infrastructure firm Moov to enable stablecoin services for over 1,000 community banks and credit unions in the United States. The Sept. 10 agreement connects Coinbase’s digital asset infrastructure with Moov’s existing payment systems, allowing smaller financial institutions to offer stablecoin services without building separate crypto technology.
Coinbase connects Stablecoins with banking rails
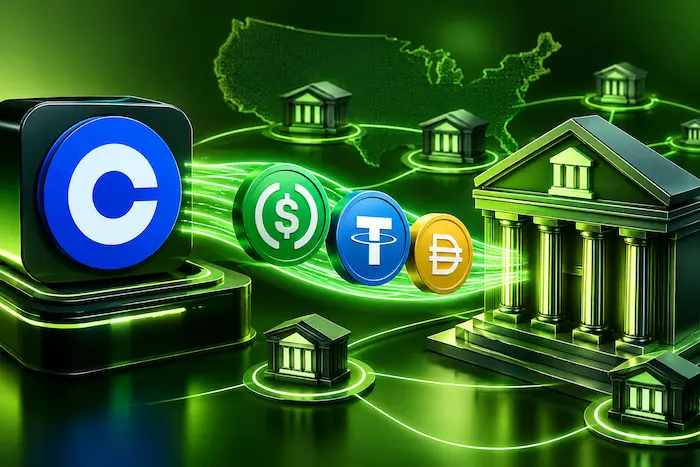
Under the agreement, Moov will integrate Coinbase’s stablecoin infrastructure into its payments platform. The arrangement will allow participating institutions to add consumer payments, merchant acceptance, settlement and payouts through existing systems.
Banks benefit from crypto.
We're partnering with @Moov to provide small and community banks the infrastructure for stablecoins.
That means acceptance, settlement, and real-time funding for more than 1000 of them, through the tech stacks they already use.
This is what regulated… pic.twitter.com/sS8NNIVZBF
— Coinbase 🛡️ (@coinbase) September 10, 2026
Moov plans to use Coinbase Developer Platform custodial wallet accounts to hold funds. Its integration will also use Coinbase’s Payments API to manage stablecoin transfers and settlement.
The companies have not announced a commercial launch date or identified the first participating banks. They also have not disclosed which stablecoins or blockchain networks the service will support.
Coinbase will provide the digital asset infrastructure, while Moov will connect those capabilities with financial institutions already using its payment technology.
Community banks gain access without new systems
The partnership targets a growing demand from businesses seeking stablecoin payment options from their primary financial institutions. Moov CEO Wade Arnold said some business customers already leave their banks when they need stablecoin acceptance or disbursement services.
The new model aims to keep those relationships within existing banking channels. Therefore, participating institutions would not need to develop their own blockchain custody systems or payment infrastructure.
The planned services include several key functions
- Consumer stablecoin payments
- Merchant payment acceptance
- Merchant settlement
- Business payouts
- Real-time funding
Ryan VanGrack, a Coinbase vice president, said customers of regional banks and credit unions have used digital assets for years. He said the partnership can bring related services into existing financial systems.
However, important commercial details remain unclear. The companies have not disclosed transaction fees, conversion costs, insurance treatment or customer eligibility requirements.
Regulatory shift raises stakes for banks
The partnership arrives as US regulators establish clearer rules for financial institutions engaging with digital assets. In March 2025, the Office of the Comptroller of the Currency approved national banks and federal savings associations to engage in some crypto custody, stablecoin-reserve and payment activities.
In July 2025, Congress also established a federal framework for payment stablecoins with the GENIUS Act. The law sets forth requirements for issuers and the minimum level of reserves that must be established.
Meanwhile, there are alternatives being developed by major U.S. banks. U.S. Bank recently completed a live cross-border test involving its proprietary USBDC stablecoin on the Stellar blockchain.
A separate group of major financial institutions has also announced plans for a company focused on issuing stablecoins. That effort includes Bank of America, Citi, Goldman Sachs, Deutsche Bank and UBS.
The Coinbase-Moov model differs because it focuses on infrastructure rather than asking each community bank to issue its own token.
The banks are taking different approaches to stablecoins
While major banks are developing a different issuing model, U.S. Bank is experimenting with its own USBDC stablecoin. Instead, Coinbase and Moov provide shared infrastructure community banks can use, without having to develop their own tokens.
The disparity might make the partnership more accessible to smaller institutions. But banks that decide to join will still have to handle the custody, transaction monitoring and compliance, customer protection needs.
It also extends Coinbase’s contribution to the traditional financial infrastructure. As acceptance increases, additional banking institutions might not invest heavily in their own blockchain programs instead of relying on outside stablecoin platforms.
Stablecoin adoption faces banking risks
The arrangement could give smaller institutions faster access to digital payment infrastructure. It could also help community banks respond to businesses that increasingly seek blockchain-based payment options.
Stablecoins can move dollar-linked value continuously, including outside traditional banking hours. Yet their stability remains dependent on their backing, redemption mechanisms and operational controls.
Community banking groups have also raised concerns about stablecoins competing with traditional deposits. The Independent Community Bankers of America has warned that deposit migration could weaken funding available for local lending.
For now, Coinbase and Moov have not provided a timetable for bringing the service to customers. The companies instead plan to develop the integration while exploring additional connections between stablecoins and financial products offered by regional institutions.
Conclusion
Coinbase is extending stablecoin infrastructure beyond crypto-native businesses and toward the US community banking sector. Moov provides the existing payment network, while Coinbase supplies custody and blockchain transaction capabilities.
The partnership could lower the technology barrier for smaller institutions. Its success will depend on regulatory compliance, customer demand, costs and the safeguards adopted during implementation.